Rat-infested property is “suitable for use as a dwelling”
The First-tier Tribunal has found that a property in disrepair, inhabited by rodents, is still suitable for use as a dwelling for tax purposes. This sounds illogical - so what’s the full story?
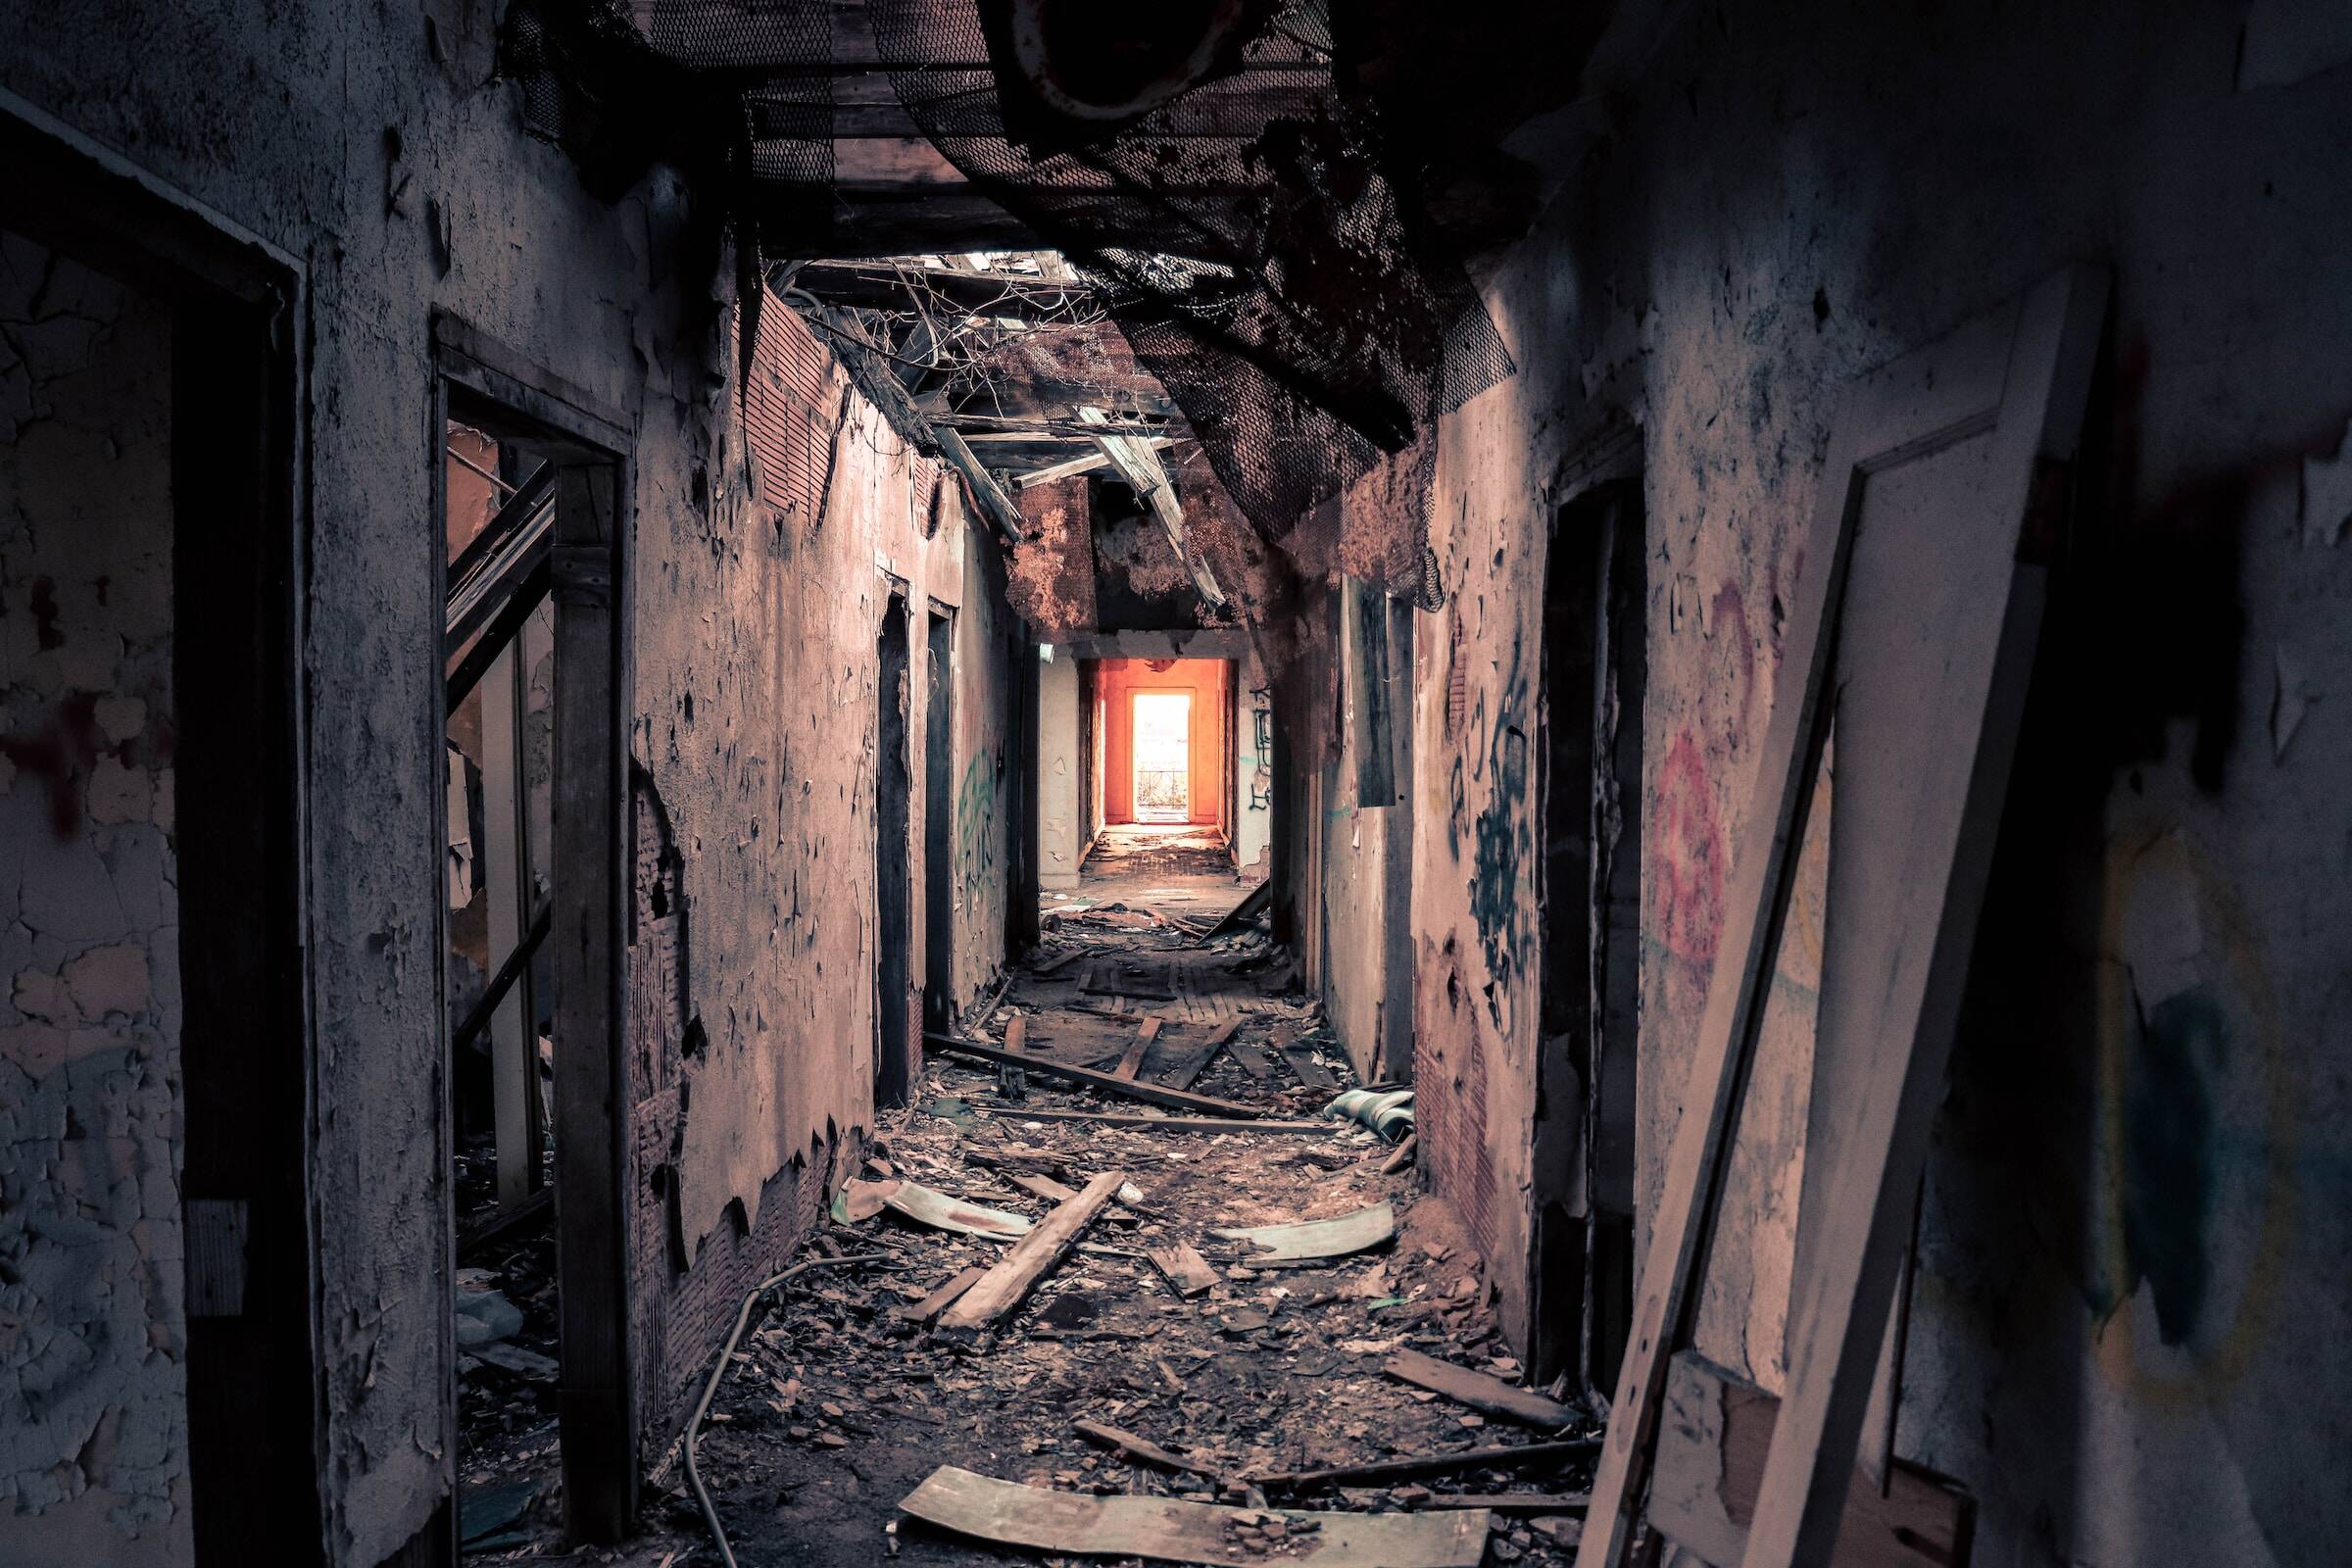
In Mudan & Anor v HMRC the taxpayers (the Ms) purchased a £1.7m property in London that had been empty for five months after the previous tenants were evicted. During that time, the property had been broken into and vandalised, none of the utilities worked and mice and rat droppings covered the kitchen. The boiler had been ripped off the wall, the gas, electricity and water were not functioning safely and rainwater was leaking into the property. It took nine months of renovations before the Ms moved into the property.
Higher rates of stamp duty land tax (SDLT) are chargeable on residential properties, with the pertinent part of the definition being that the property is residential if it is “suitable for use as a dwelling”. Due to the state of the property, the Ms argued that it was not suitable to be occupied and so lower rates of SDLT should apply. HMRC, and ultimately, the tribunal disagreed. The judge confirmed that the bar for a property not to be suitable for use as a dwelling was set very high, and that a building which was recently used as a dwelling, has not in the interim been adapted for another use, and is capable of being so used again will count as a dwelling for SDLT purposes. An additional £100,000 SDLT was due on the purchase, and the appeal was dismissed.
Related Topics
-
Company buying back shares? Watch out for forthcoming changes
Company owners arranging a retirement, a family succession or a shareholder exit may need to rethink how shares are bought back. The Budget confirms that the government intends to tighten the rules distinguishing capital gains from dividend income, potentially making some buybacks considerably more expensive. How might an ordinary business exit be caught?
-
What can you learn from HMRC’s input tax toolkit?
You know that penalties can be charged on careless errors and many mistakes relate to input tax being wrongly claimed. How can HMRC’s input tax guidance help your business to claim the right amount?
-
A £3,000 side-hustle allowance: more generous than it looks?
People making money from small side businesses will have more room to earn without paying income tax, following a Budget decision to triple the trading allowance. However, the figure relates to what you receive before expenses, not the profit you keep. Will the £3,000 allowance actually save you tax?